Key Takeaways
Many insurance plans cover visits with a registered dietitian, often as a preventive benefit that costs you $0. Coverage depends on your specific plan.
The credential matters. Insurers typically reimburse a registered dietitian (RD/RDN), as well as certified nutrition specialists (CNS) in some states, not an uncredentialed “nutritionist,” so confirm the provider is an RDN or CNS.
Call the number on your insurance card and ask about “medical nutrition therapy,” your deductible, copay, and whether a referral is required.
Always confirm a dietitian is in-network for your exact plan before you book, and ask for an estimated cost so there are no surprises.
If your dietitian is out-of-network, ask about a superbill, HSA/FSA payment, or a platform that checks your coverage for you.
Wondering how to find a dietitian that takes your insurance without a surprise bill later? You are not alone, and the process is more straightforward than it looks. This guide walks you through confirming your benefits, asking your insurer the right questions, and finding an in-network registered dietitian you can actually book. We will decode the benefits language along the way, from medical nutrition therapy to deductibles and copays.
Working with a registered dietitian covered by insurance can make evidence-based nutrition care part of your regular healthcare, not a luxury. The key is knowing what to check before your first visit.
On this page
Does insurance actually cover a dietitian?
How to find a dietitian that takes your insurance, step by step
Key terms to know when checking coverage
What if my dietitian isn’t covered or in-network?
What to expect once you’re matched
Getting started with a covered dietitian
Frequently asked questions
In 30 seconds: For many people, yes — a dietitian is covered by insurance, frequently as a $0 preventive benefit. To confirm your own coverage, call your insurer, ask about medical nutrition therapy and referral rules, and verify the dietitian is in-network for your plan before you book. If they are out-of-network, a superbill, HSA/FSA, or a coverage-checking platform can help.
Does insurance actually cover a dietitian?
For many people, the answer is yes. Nutrition counseling is often a covered service, and it may cost little or nothing out of pocket. What matters is how your specific plan defines the benefit.
Because coverage varies by plan, treat the sections below as a map for what to check, not a guarantee. Your exact benefits, network, and costs depend on your individual policy.
What “covered” usually means: preventive vs. diagnosis-based coverage
Under the Affordable Care Act, most plans must cover a set of preventive services at no cost to you when you see an in-network provider, even before you meet your yearly deductible.
Some nutrition visits fall under this preventive umbrella, so they may be free for eligible members. Other visits are covered on a diagnosis basis, meaning your plan pays because you have a condition like diabetes, high cholesterol, or a digestive disorder. Whether your plan treats a visit as preventive or diagnosis-based affects your cost, so it is worth asking directly.
Registered dietitian vs. nutritionist: why the credential affects coverage
This distinction matters more than most people expect. A Registered Dietitian Nutritionist (RDN) is a licensed medical professional with years of clinical training, qualified to treat and manage medical conditions. The title “nutritionist,” by contrast, can be used without formal credentials in some states. It is important to note that in some states, a Certified Nutrition Specialist (CNS) is also a credentialed medical professional.
Insurers typically reimburse care from a credentialed registered dietitian and CNS (in some states), not from someone using the general “nutritionist” label. So when you check coverage, confirm the provider is an RD, RDN or CNS. If you want a deeper breakdown, see our guide on the difference between a nutritionist and a dietitian.
Medicare and Medicaid coverage in brief
Medicare covers medical nutrition therapy for specific conditions, including diabetes and kidney disease, or a kidney transplant in the last 36 months, when a doctor refers you. A referral from your treating provider is generally part of qualifying.
Medicaid coverage for nutrition services varies by state, since each state administers its own program. If you have Medicaid, check your state’s specific benefits or ask a provider to verify coverage for you. As always, what applies to you depends on your plan and state.
The same is true for commercial and marketplace plans. Two people with the same insurer can have different nutrition benefits depending on their employer, plan tier, and state. That is why the steps below focus on confirming your own coverage rather than relying on a general rule.
below focus on confirming your own coverage rather than relying on a general rule.
How to find a dietitian that takes your insurance, step by step
Here is the practical part. Follow these five steps in order, and you will know exactly what you will pay before you sit down for your first session.
Step 1: Confirm what your plan covers
Start with your insurance card. Call the member services number on the back and have your plan details ready. Ask whether your plan covers nutrition counseling or medical nutrition therapy, and whether it is treated as a preventive benefit or requires a diagnosis.
Write down who you spoke with and when. Coverage answers can vary between representatives, so a paper trail helps if a claim is ever questioned.

Step 2: Ask the right questions
The goal here is to leave the call with no unknowns. Ask these questions directly:
Is medical nutrition therapy (CPT codes 97802 and 97803) a covered benefit on my plan?
Do I need a physician referral or prior authorization before my first visit?
Is this covered as preventive care, or only with a qualifying diagnosis?
How many visits does my plan cover per year?
What will I owe: a copay, coinsurance, or the full rate until I meet my deductible?
If any answer is unclear, ask the representative to repeat it and note the reference number for the call.
Step 3: Search for in-network registered dietitians
Once you know your benefits, look for an in-network registered dietitian who fits your needs. You can use your insurer’s online provider directory, ask your doctor for a referral, or use a platform that verifies coverage and matches you with a covered RD.
Filter for someone who specializes in your goals, whether that is diabetes, gut health, PMOS, prenatal nutrition, or your relationship with food. Specialization means the guidance is tailored to you, not generic.
Step 4: Verify the dietitian is in-network before you book
Never assume a directory listing is current. Provider networks change, so confirm the specific dietitian is in-network for your exact plan on the date you will be seen.
Verify it two ways when you can: check with the dietitian’s office and confirm with your insurer. This double-check is the single best way to avoid an out-of-network surprise.
When booking with Berry Street, this step is done for you when matching you with a dietitian.
Step 5: Understand your estimated cost before your first visit
Ask for a cost estimate in writing before you book. You should know whether you owe $0, a copay, or a portion of the rate toward your deductible. A trustworthy provider will show you this clearly and flag anything uncertain.
At Berry Street, we start by helping you understand your cost first. You can check your coverage in about 60 seconds by entering your state and insurance provider, with no commitment. We are in-network with 1,250+ insurance plans, and 95% of our members pay $0 with coverage.
Key terms to know when checking coverage
Benefits language can feel like a different vocabulary. Here is a plain-language glossary for the terms you will hear most.
Medical nutrition therapy (MNT): Evidence-based nutrition counseling provided by a registered dietitian, often billed under specific codes and sometimes covered as preventive care.
In-network: A provider who has a contract with your insurer, which usually means lower costs for you.
Deductible: The amount you pay out of pocket each year before your plan starts sharing costs.
Copay: A fixed fee you pay for a covered visit, such as $25 per appointment.
Coinsurance: A percentage of the visit cost you pay after meeting your deductible, such as 20%.
Referral: A note from your doctor recommending a specialist, which some plans require before they cover a visit.
Preventive benefit: A category of covered services many plans must provide at no cost to you when delivered in-network.
“When a client isn’t sure about their coverage, I tell them to call the number on their card and ask four things word for word: Is medical nutrition therapy covered, do I need a referral first, is it preventive or diagnosis-based, and how many visits do I get per year? Then write down the representative’s name and the call reference number. That call asking those specific questions can save people from a surprise bill later.” — Bridget Isaacs, MS, RD
What if my dietitian isn’t covered or in-network?
Sometimes the dietitian you want is not in your network, or your plan does not cover nutrition counseling. You still have good options, and none of them require giving up on care.
Out-of-network options: superbills, HSA, and FSA
If you see an out-of-network registered dietitian, ask for a superbill. A superbill is an itemized receipt you submit to your insurer, and some plans reimburse part of the cost for out-of-network care. Ask your plan about your out-of-network benefits before you book.
You can also often pay with a health savings account (HSA) or flexible spending account (FSA), since nutrition counseling that treats a diagnosed condition is typically an eligible expense. Check your account rules to confirm what qualifies for you.
Why a platform that checks coverage for you removes the guesswork
Calling your insurer works, but it takes time and patience. A platform that verifies your benefits for you can remove most of that legwork by confirming coverage and matching you with an in-network registered dietitian.
That is the approach we take at Berry Street. We check your coverage against 1,250+ insurance plans and show you your expected cost up front, so whether insurance covers nutrition counseling stops being a mystery. Most members pay $0, and there is no commitment to check.
The point is not to pressure you into one path. It is to make an informed choice easier, so cost is not the thing that keeps you from care you may already have access to.
What to expect once you’re matched with a covered dietitian
Knowing what happens next takes the pressure off. Care with a registered dietitian is collaborative, personalized, and built around your real life.
Your first session and follow-ups
Your first visit is usually a conversation, not a lecture. Your dietitian asks about your health history, your goals, your schedule, and your relationship with food, then works with you on a realistic plan. You can read more about what to expect when seeing a dietitian before you start.

Follow-up visits track what is working and adjust what is not. Appointment cadence is personal, so you and your dietitian decide together how often to meet.
How personalized, insurance-covered care beats one-size-fits-all diet advice
Generic diet advice fails many people because it ignores the individual. If calorie-counting apps and rigid plans worked “until they didn’t,” that is a one-size-fits-all problem, not a willpower problem. A registered dietitian tailors care to your body, your life, and the outcomes you care about, whether that is steadier energy, better blood glucose, easier digestion, or a calmer relationship with food.
Weight can be part of your goals, but it does not have to be, and it is not the only measure of health. This personalized model is also what the evidence supports. The Academy of Nutrition and Dietetics has documented that medical nutrition therapy delivered by registered dietitians improves outcomes and is a recognized, effective clinical service. To see how this works in practice, read how a dietitian helps a patient.
“So many people tell me they put off seeing a dietitian for years because they assumed it would cost a fortune out of pocket. That is why it is important to check coverage, because you may be surprised. Majority of the clients I see pay nothing because their plan covers it as preventive care. Don’t let a guess about the price keep you from care that’s often included in your benefits.” — Bridget Isaacs, MS, RD
cluded in your benefits.” — Bridget Isaacs, MS, RD lockquote>
Getting started with a covered dietitian
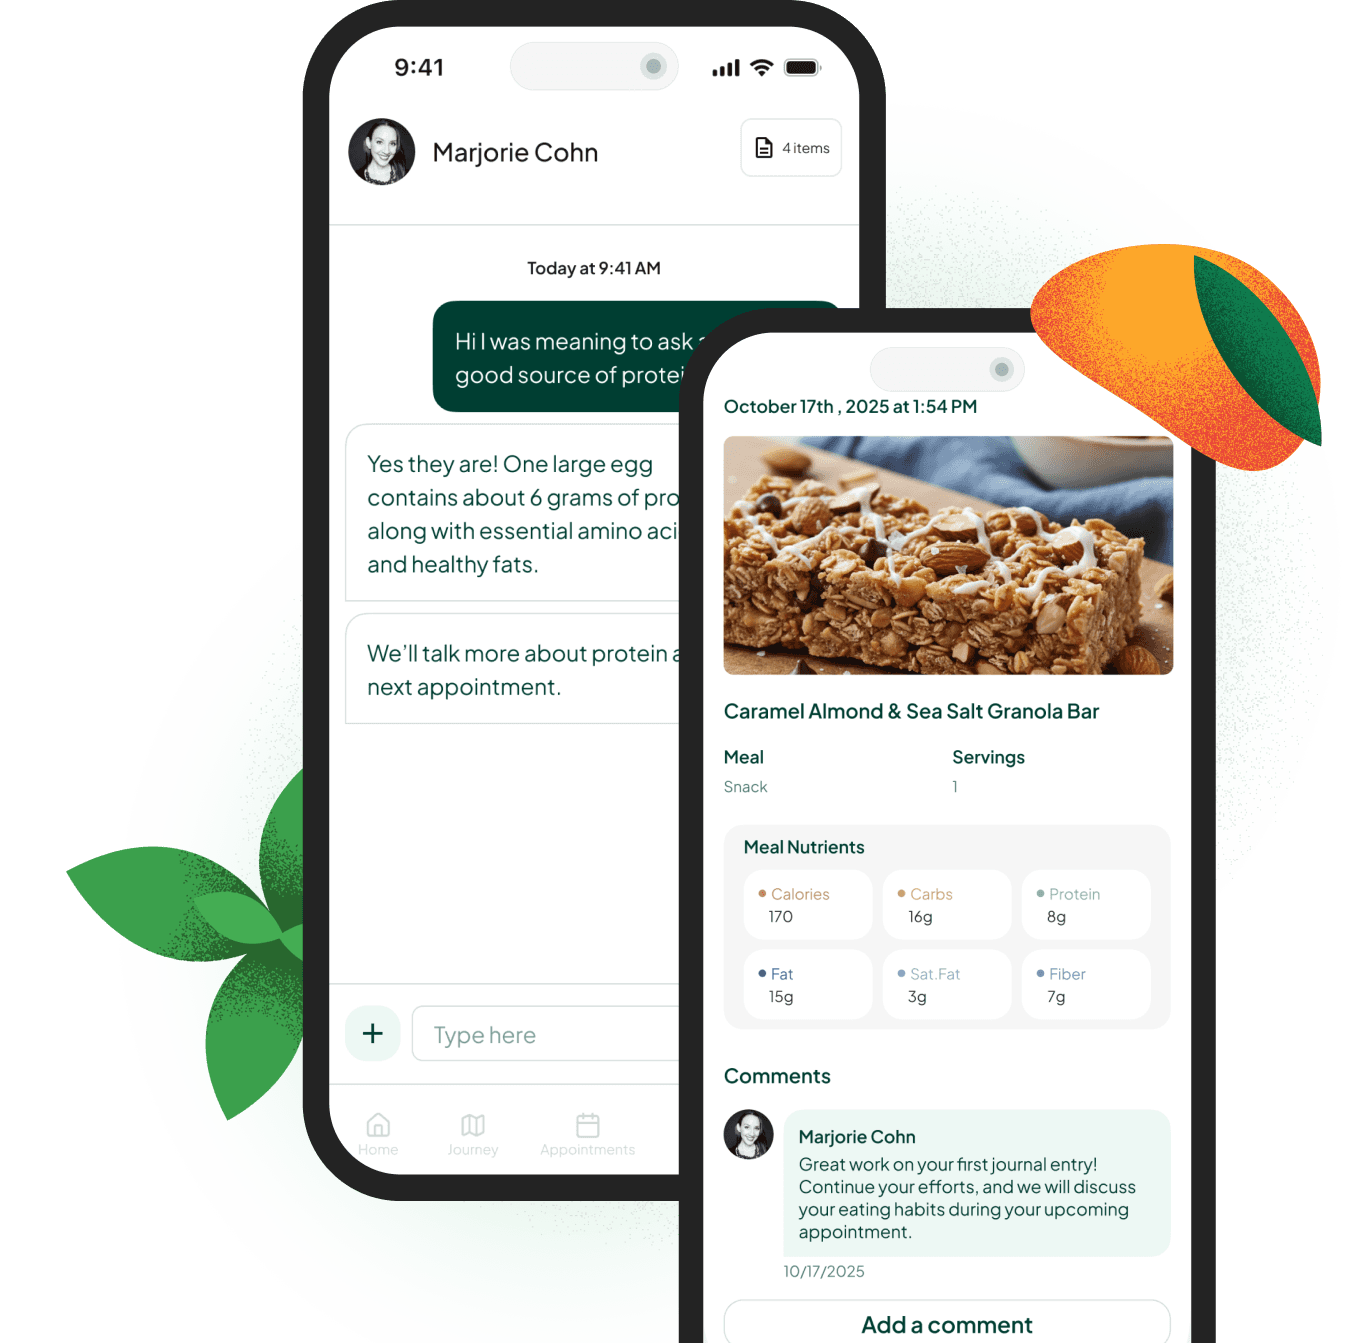
If you have been meaning to talk to a registered dietitian, the first step is simple: find out whether you are covered. You can check your coverage in about 60 seconds with no commitment, then decide from there.
We match you with an online dietitian covered by insurance who specializes in your goals and health history. Visits are fully virtual, so there is no commute and no waiting room, and most members pay $0 with coverage.
Frequently asked questions
Does insurance cover seeing a dietitian?
Often, yes. Many plans cover visits with a registered dietitian, sometimes as a $0 preventive benefit and sometimes when tied to a diagnosis. Coverage depends on your specific plan, so confirm your benefits with your insurer or a platform that checks for you.
Does Medicare cover a dietitian?
Medicare covers medical nutrition therapy for certain conditions, including diabetes and kidney disease, when referred by a doctor. A physician referral is generally required to qualify.
Does Medicaid cover a nutritionist?
Medicaid coverage for nutrition services varies by state, since each state runs its own program. Some states cover visits with a registered dietitian, and requirements differ. Check your state’s Medicaid benefits or ask a provider to verify coverage for you.
Do I need a doctor’s referral to see a dietitian?
It depends on your plan. Some insurers require a physician referral before they cover nutrition counseling, and others do not. Ask your insurer directly, and confirm before your first visit to avoid a denied claim.
Is a dietitian covered by insurance for preventive care, or only with a diagnosis?
Both are possible, depending on your plan. Under the Affordable Care Act, many plans must cover eligible preventive services at no additional cost when you see an in-network provider. Other plans cover nutrition visits only with a qualifying diagnosis, so ask which category applies to you.
How much does a dietitian cost with insurance?
It varies by plan. With coverage, you may pay $0, a copay, or coinsurance, and without coverage, you would pay the provider’s rate. At Berry Street, 95% of members pay $0 with coverage, though your cost depends on your individual plan.
What questions should I ask to confirm a dietitian is in-network?
Ask your insurer whether the specific dietitian is in-network for your exact plan on your visit date. Also ask whether medical nutrition therapy is covered, whether you need a referral, and what you will owe. Confirm with both the insurer and the provider’s office.
What’s the difference between a dietitian and a nutritionist for insurance coverage?
A registered dietitian (RD/RDN) is a credentialed, licensed medical professional, while “nutritionist” can be an unregulated title in some states. Insurers typically reimburse care from a registered dietitian, and in some states, certified nutrition specialists. That credential is often what makes a visit eligible for coverage.
How do I find an online dietitian covered by insurance?
Confirm your benefits, then use a platform or directory that verifies in-network status. An online dietitian covered by insurance offers the same credentialed care as in-person visits, delivered virtually. At Berry Street, you can check coverage in about 60 seconds and get matched with a covered RD.
What happens if my dietitian isn’t in-network?
You have options. Ask for a superbill to submit for possible out-of-network reimbursement, pay with an HSA or FSA if eligible, or use a platform that matches you with an in-network registered dietitian. Check your out-of-network benefits before booking.
How many dietitian appointments will insurance cover?
The number of covered visits per year varies by plan and, for some benefits, by diagnosis. Ask your insurer how many nutrition visits your plan allows annually. Knowing this up front helps you and your dietitian plan your follow-ups.
What happens during my first dietitian appointment?
Your first visit is usually a conversation about your health history, goals, schedule, and relationship with food. Your registered dietitian uses it to build a realistic, personalized plan with you. Follow-up visits then track progress and adjust as needed.
This article is for general education and is not a substitute for personalized medical advice. Coverage, referral requirements, and costs depend on your individual insurance plan. For guidance specific to your situation, work with a registered dietitian and confirm benefits with your insurer.